EQUAL-WEIGHTED PRICES HOLD NEAR RECORD AS VALUE-WEIGHTED INDEX PERKED UP IN SEPTEMBER 2026
CCRSI RELEASE – October 2026
(With data through September 2026)
This month's CoStar Commercial Repeat Sale Indices (CCRSI) provides the market's first look at commercial real estate pricing trends through September 2026. Based on 1,595 repeat sale pairs in September 2026 and more than 355,355 repeat sales since 1996, the CCRSI offers the broadest measure of commercial real estate repeat sales activity.
CCRSI National Results Highlights
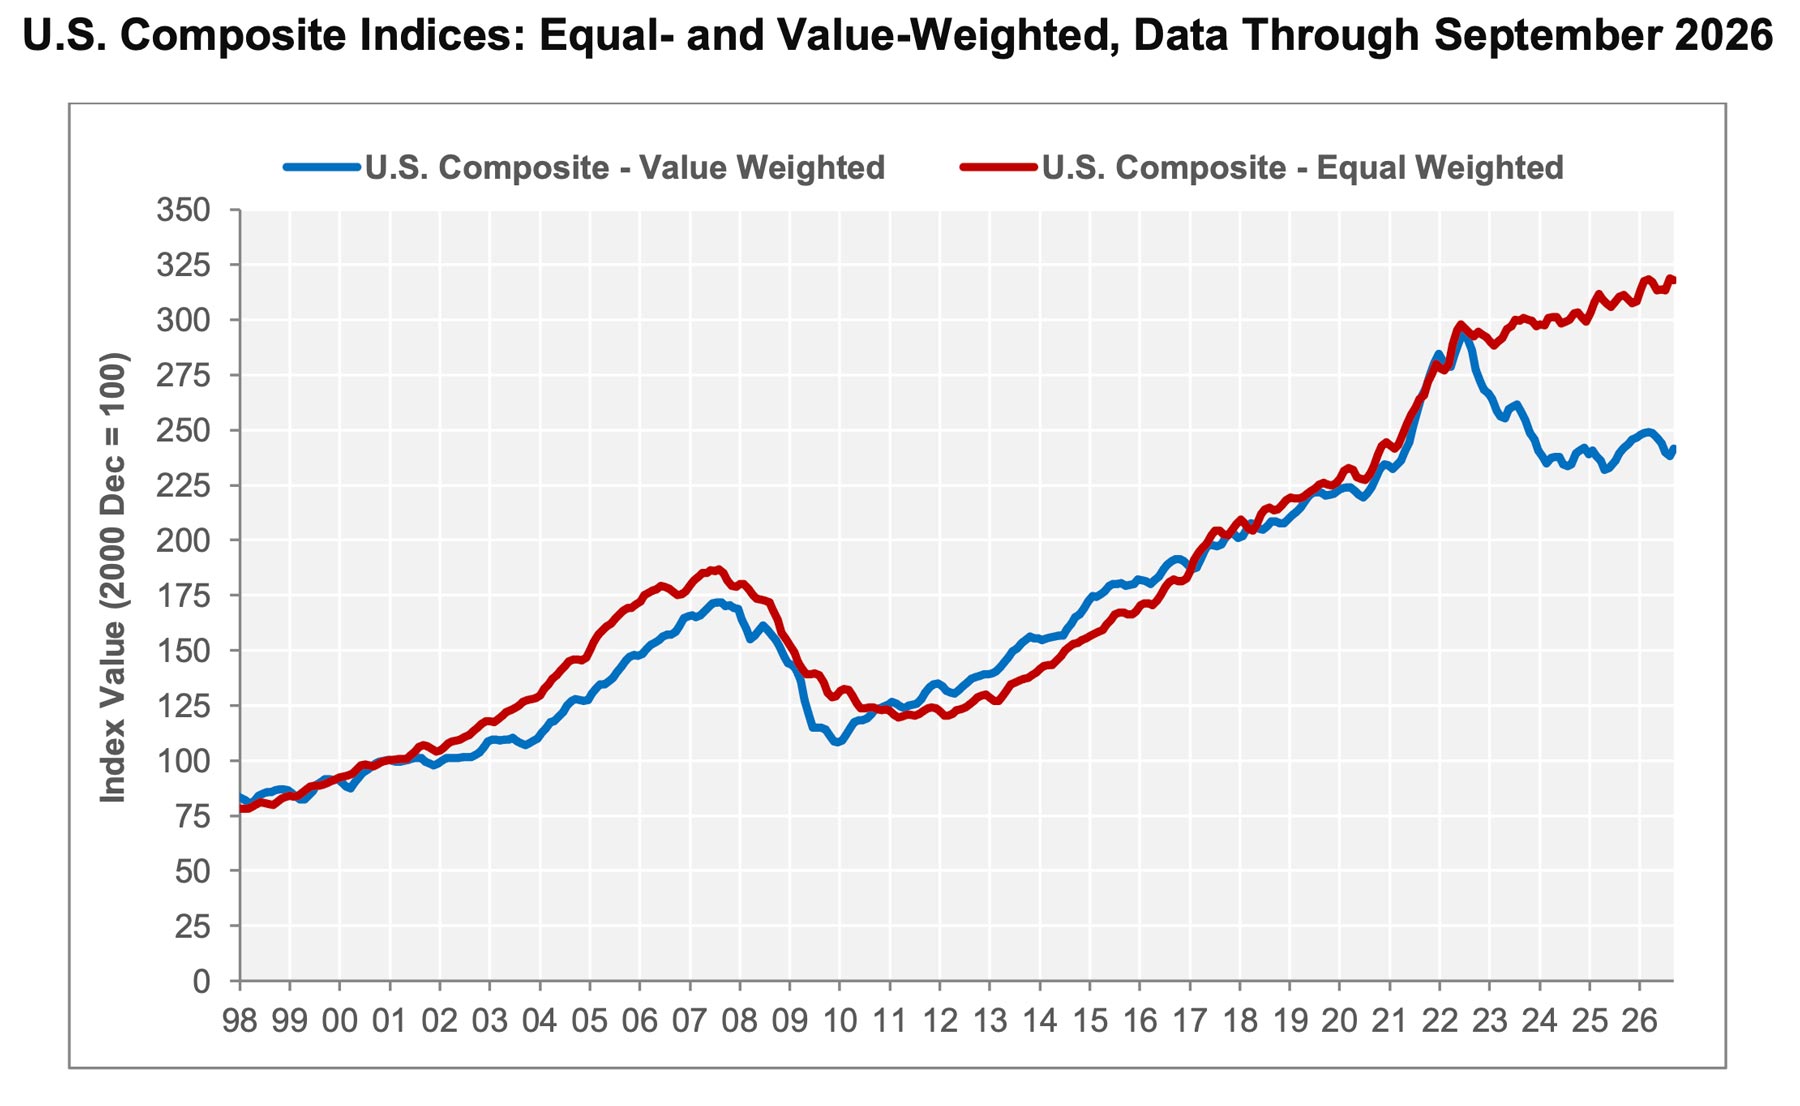
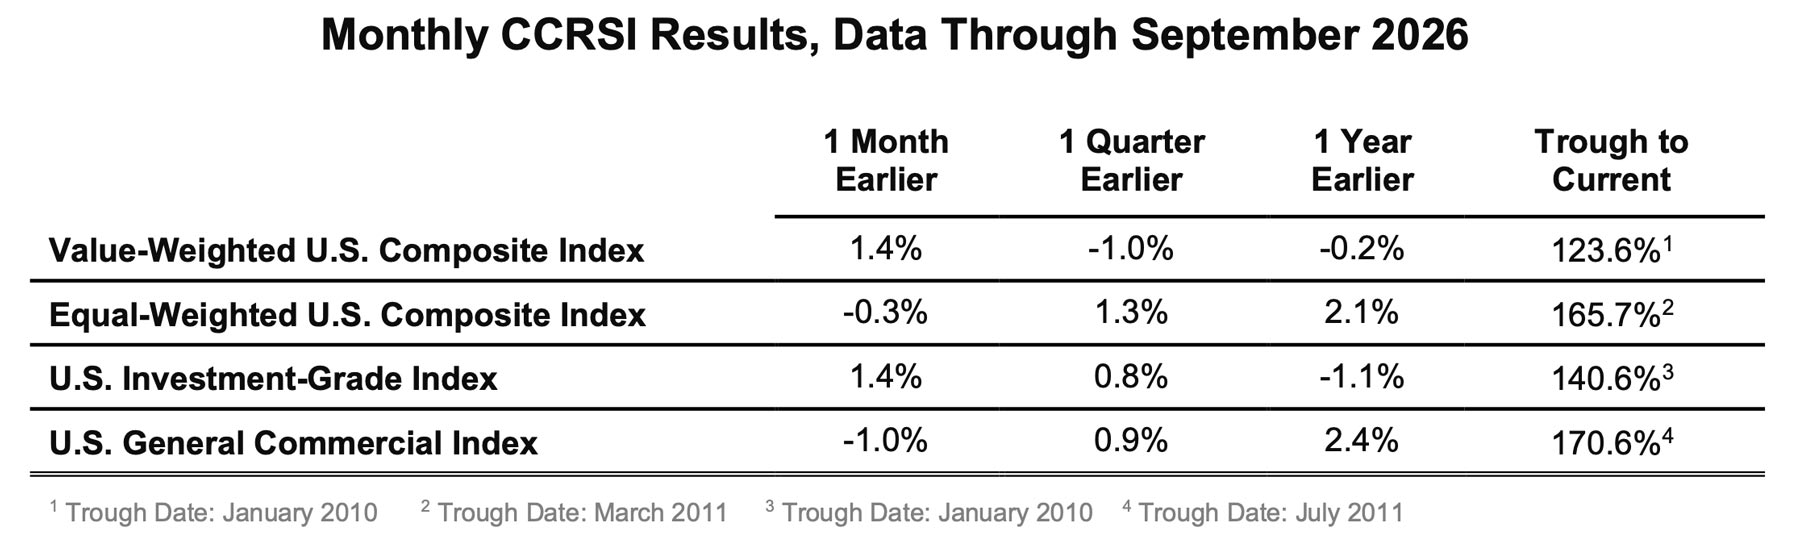
- U.S. COMPOSITE PRICE INDICES DIVERGED IN SEPTEMBER 2026. The value-weighted U.S. Composite Index, which is more heavily influenced by high-value trades common in core markets, rose 1.4% over the prior month to 242 in September 2026, ending five consecutive monthly declines from April through August 2026. Despite the monthly gain, the index was 0.2% lower than in September 2025, marking the second consecutive month of year-over-year declines. Prices in this cohort remain 17.7% below the July 2022 all-time high.
- Meanwhile, the equal-weighted U.S. Composite Index, which reflects the more numerous but lower-priced property sales typical of secondary and tertiary markets, slipped 0.3% over the prior month to 318 in September 2026. The index increased 2.1% during the 12 months ending in September 2026 compared to the 12-month period that ended in September 2025 and now sits 0.3% below its all-time high set in August 2026.
- Although equal-weighted prices have alternated between monthly gains and losses over the last two years, year-over-year price trends have been positive since March 2012 with only two exceptions: a 0.3% decline in June 2023 and a 0.3% decline in July 2024.
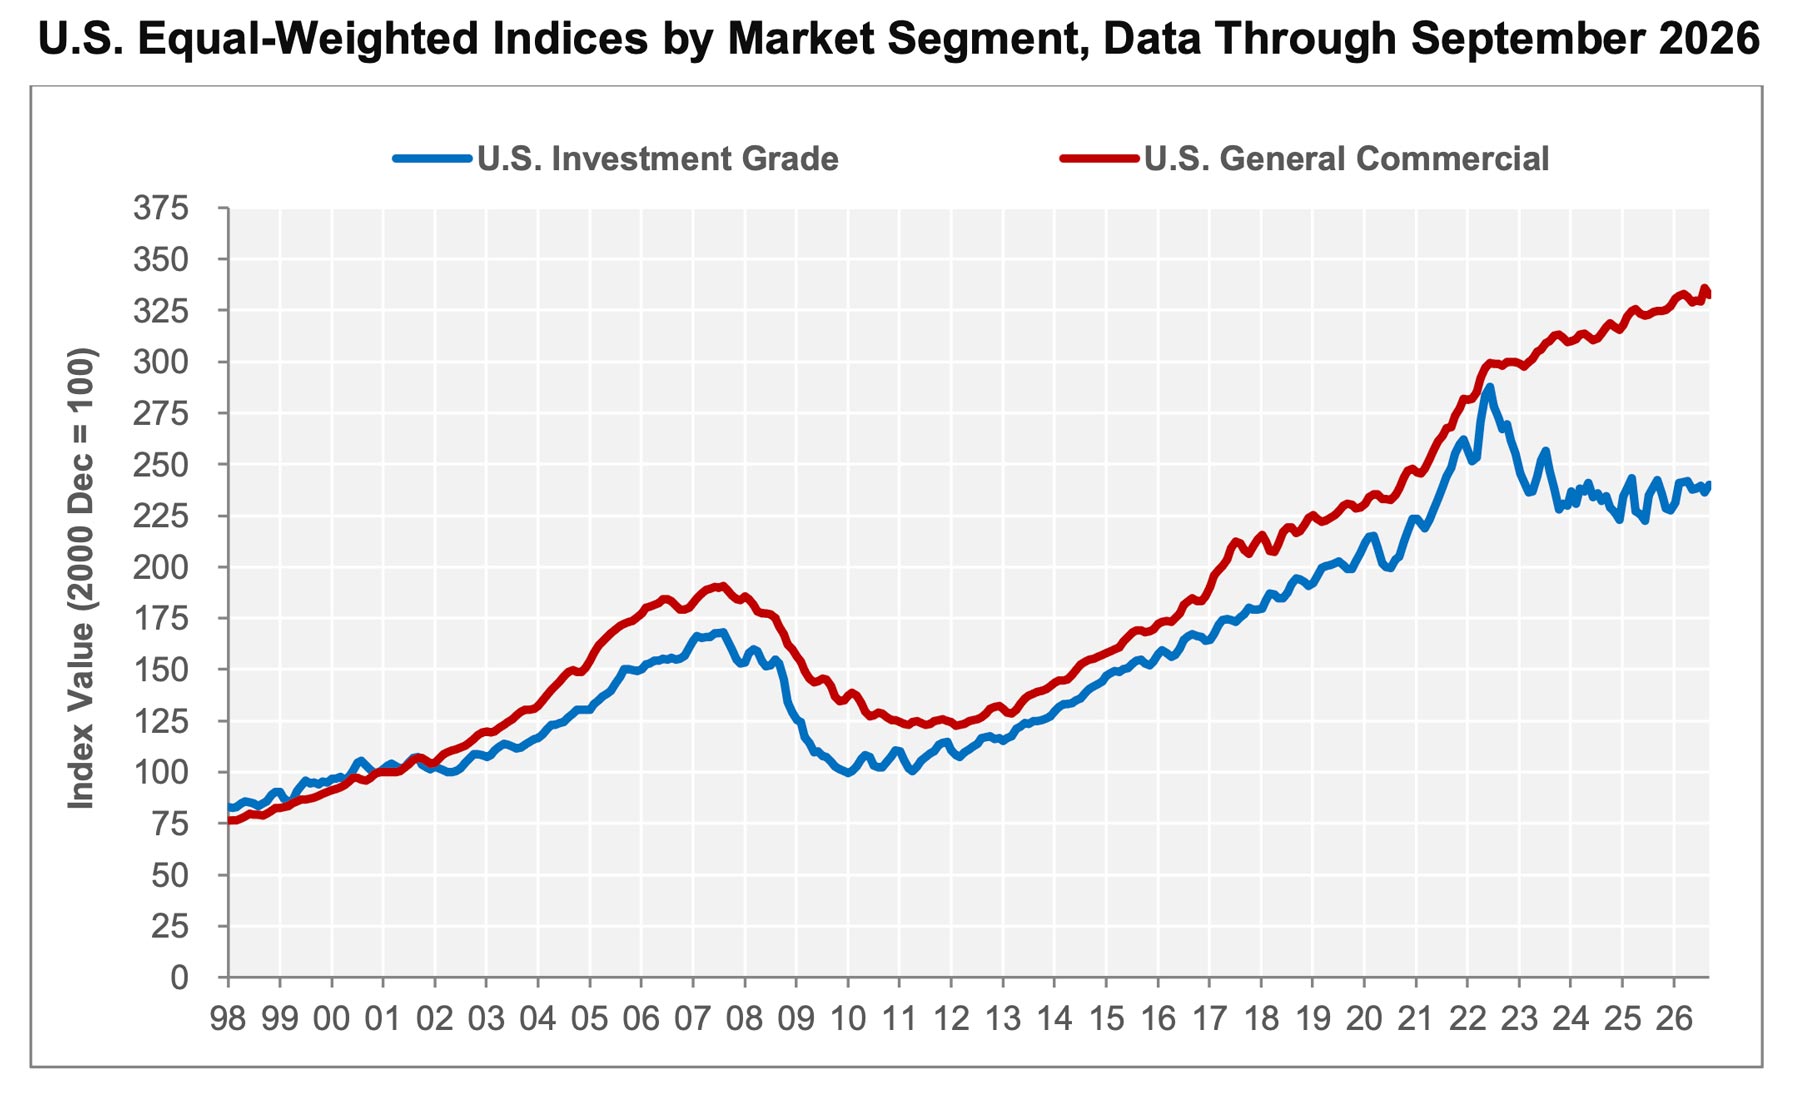
- EQUAL-WEIGHTED SEGMENTS VARIED ON AN ANNUAL BASIS IN SEPTEMBER 2026. The general commercial sub-index increased 2.4% in September 2026 compared to September 2025, while the investment grade sub-index declined 1.1% during the same period.
- On a monthly basis, the investment grade sub-index, heavily influenced by larger higher-value assets, rose 1.4% in September 2026, rebounding from a 1.3% decline in August 2026. The index remains 16.6% below its June 2022 all-time high.
- The general commercial sub-index, more heavily influenced by smaller, lower-priced assets, decreased 1.0% in September 2026 after rising 2.0% in August 2026. This sub-index now sits 1.0% below its all-time high of 336 set in August 2026.
- INVESTMENT GRADE SALES VOLUME CLIMBED IN SEPTEMBER 2026. Year-over-year, the number of investment grade repeat sales increased 1.9% in September 2026, while general commercial repeat sales declined 6.4%. The total consideration exchanged moved in opposite directions: investment grade sales volume climbed 21.6% compared to September 2025, while general commercial sales volume decreased 10.3% during the same period.
- The composite pair volume of $163.5 billion during the 12 months ending in September 2026 was 18.3% above the 12-month period that ended in September 2025. The growth in sales volume was most evident in the investment grade segment, which rose 19.7% over the 12 months that ended in September 2026 compared to the same period ending in September 2025. The investment grade segment accounted for 59.7% of the overall transaction volume during the last 12 months. The general commercial segment, which accounted for 40.3% of the 12-month transaction volume, increased 16.2% over the 12 months ending in September 2026.
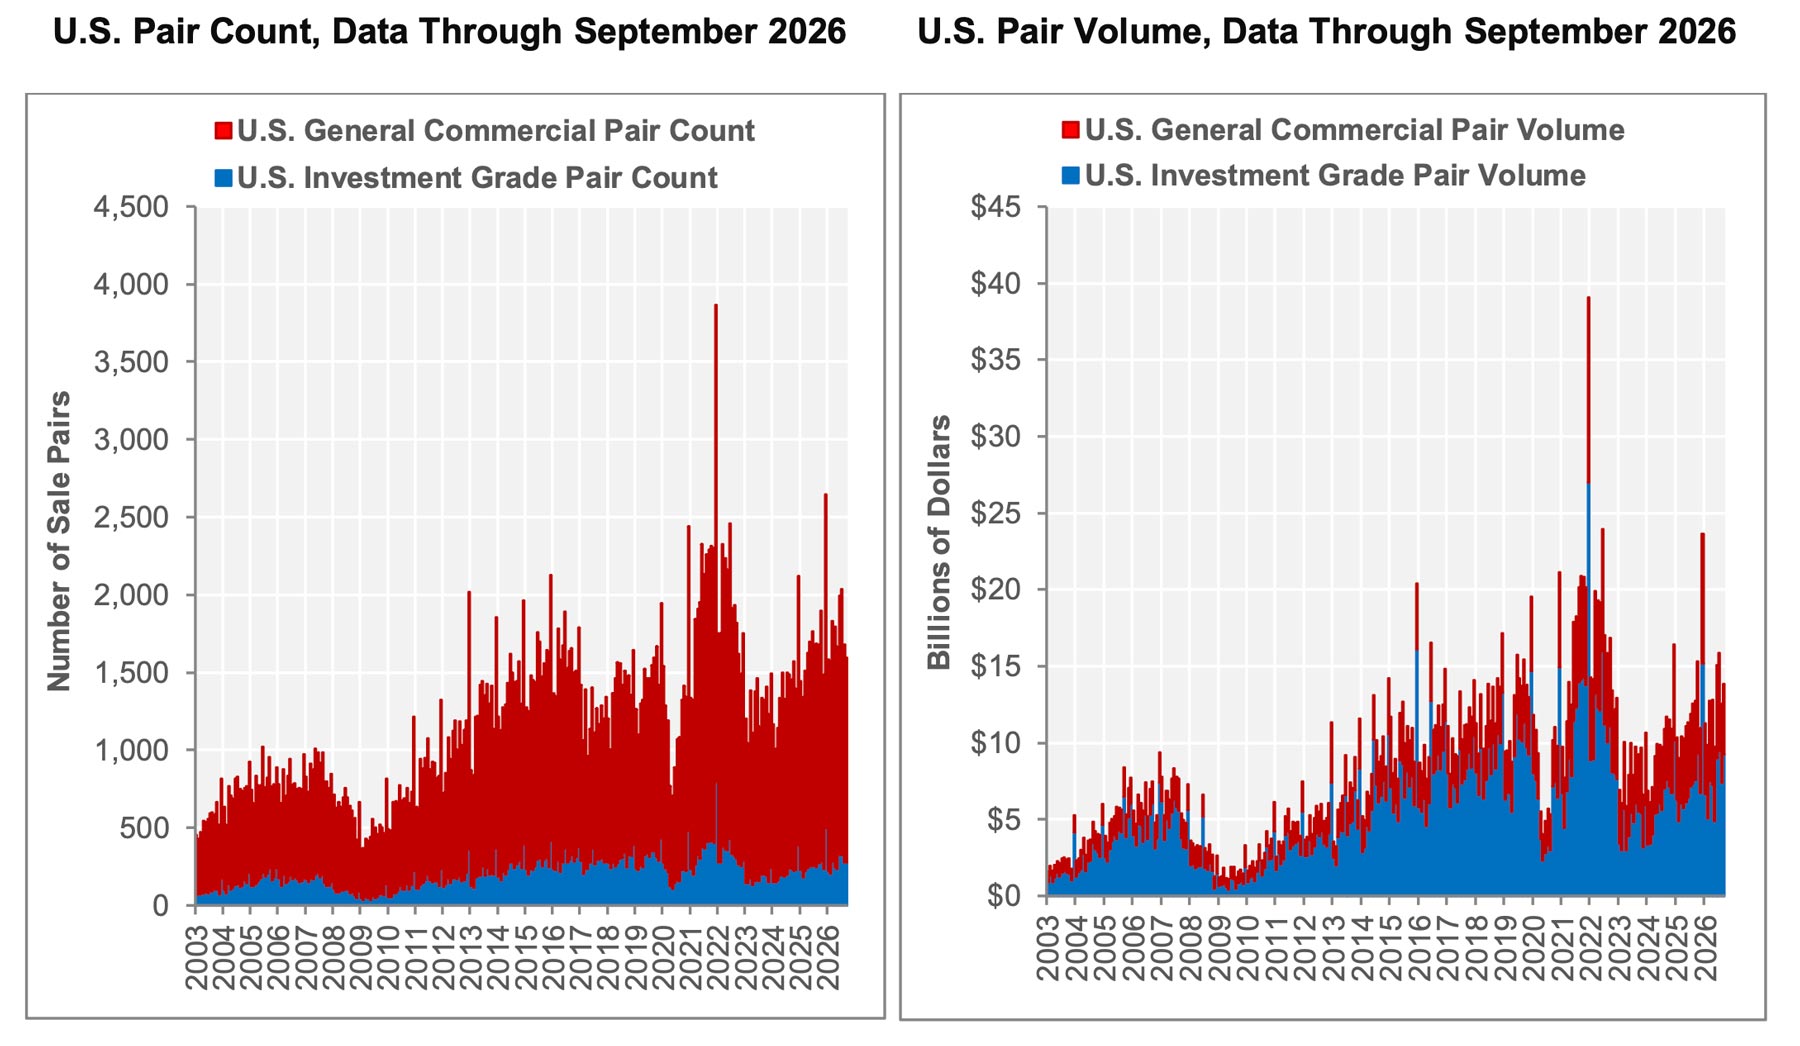
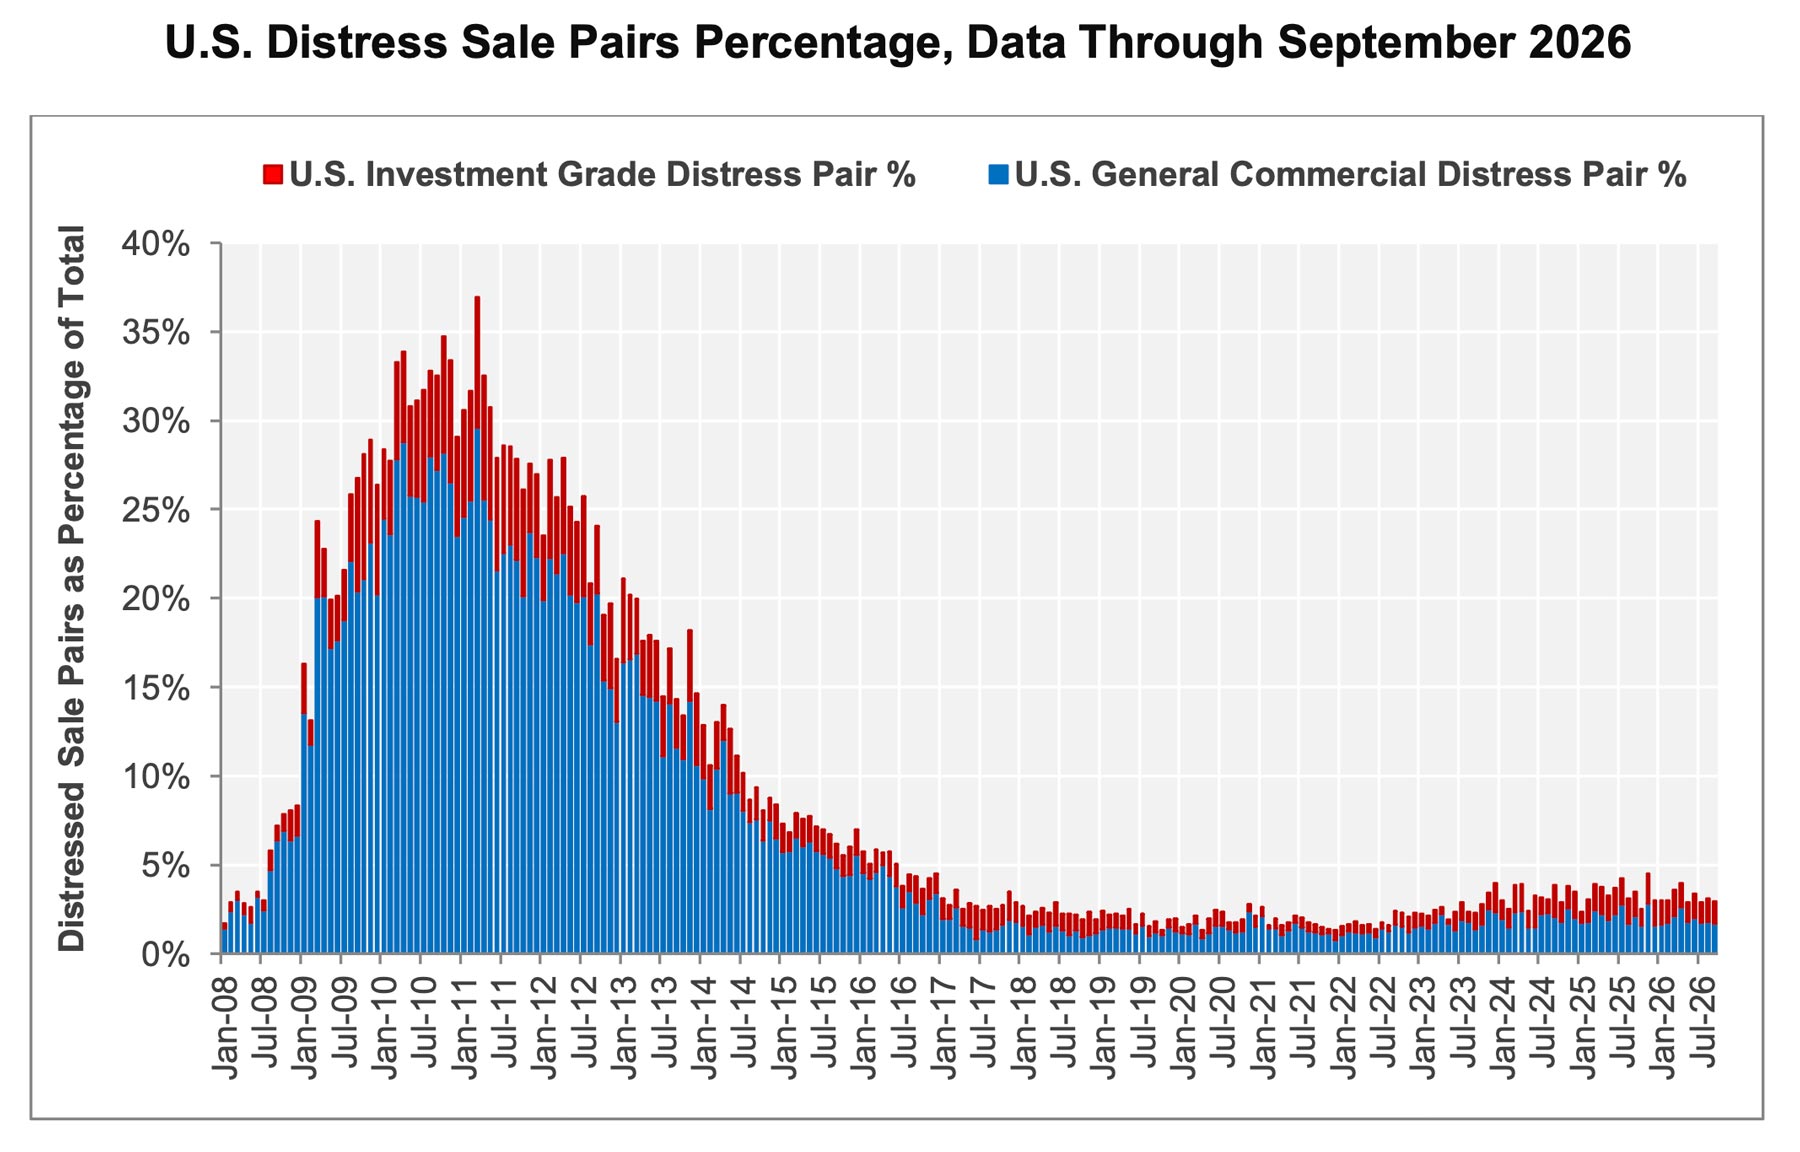
- DISTRESSED REPEAT SALES DECLINED IN SEPTEMBER 2026. Of the 1,595 repeat sales recorded in September 2026, 47 were distressed, or about 2.9% of all repeat sales. There were 27 distressed general commercial sales in September 2026, equating to 2.0% of all general commercial repeat sales. There were 20 distressed investment grade sales recorded in September 2026, accounting for 7.3% of the 275 investment grade repeat sales.
Quarterly CCRSI Property Type Results
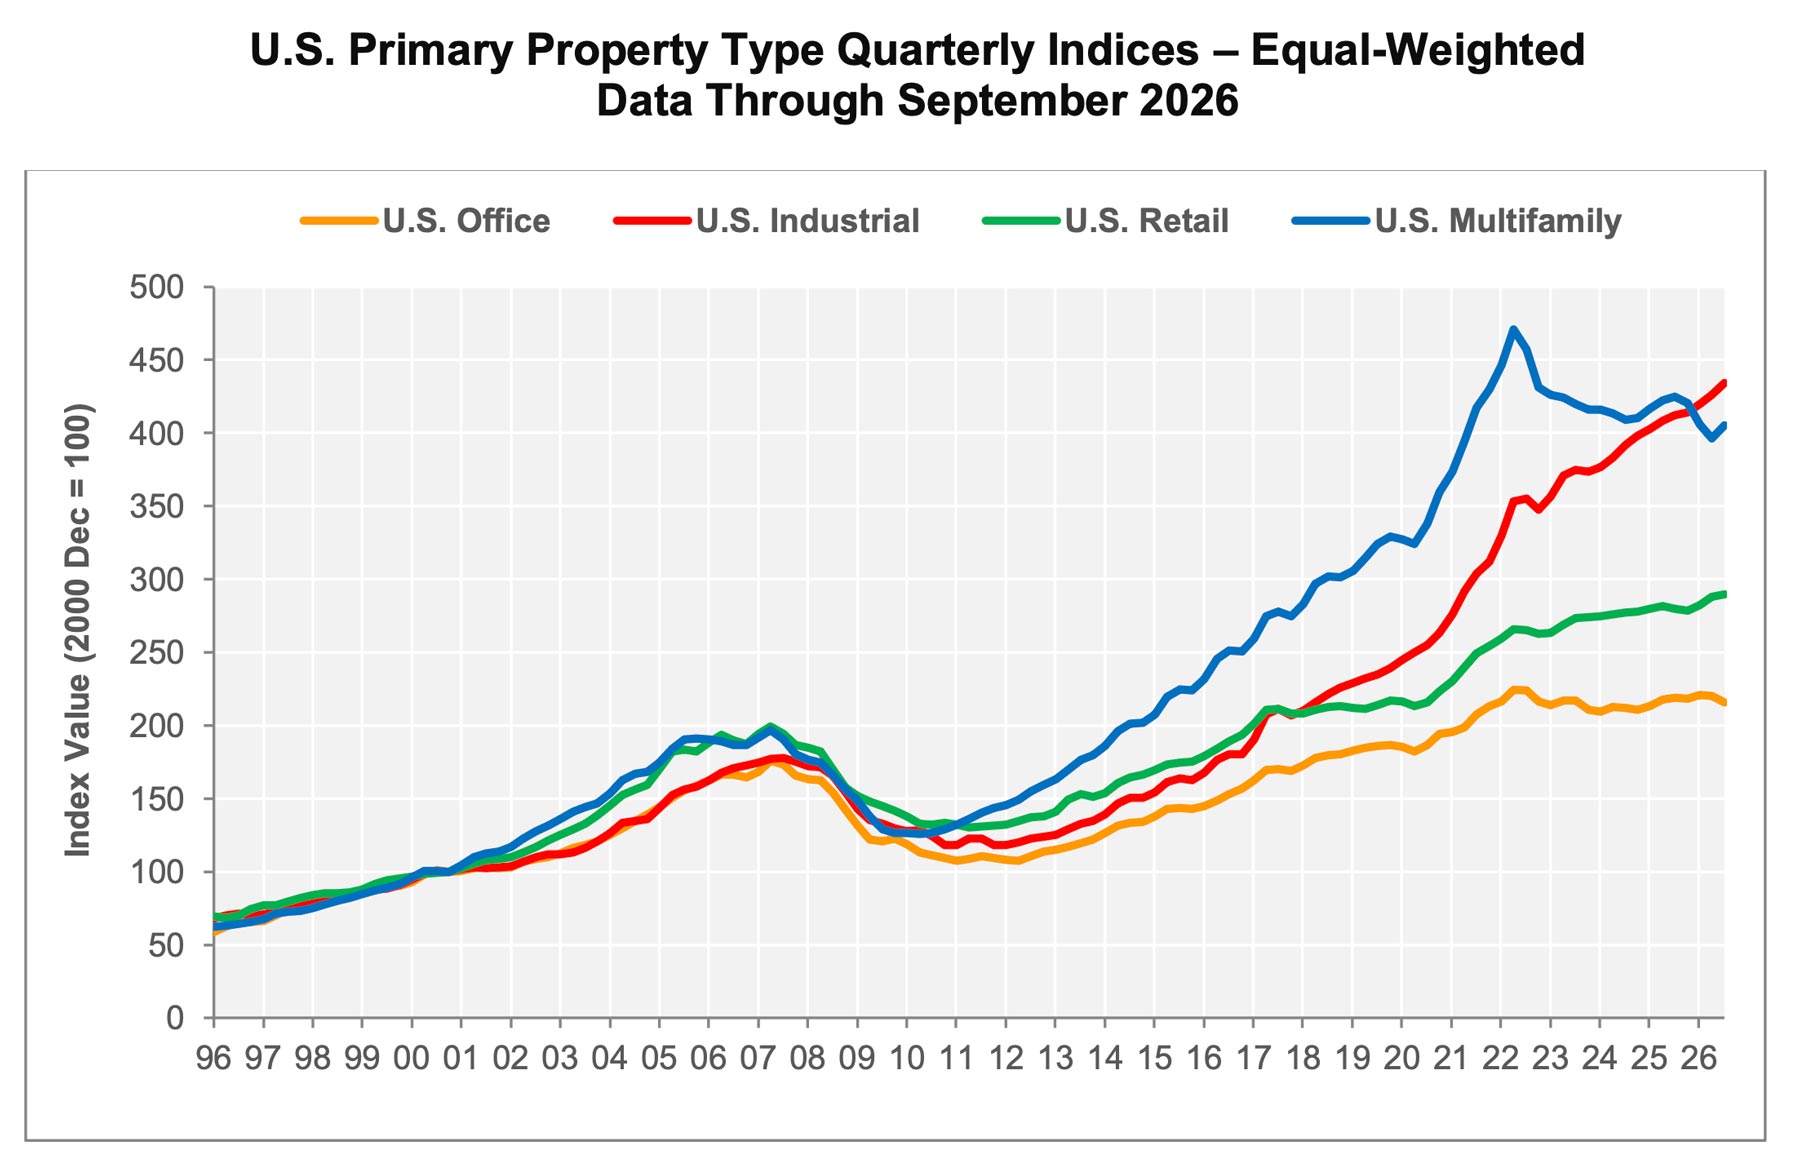
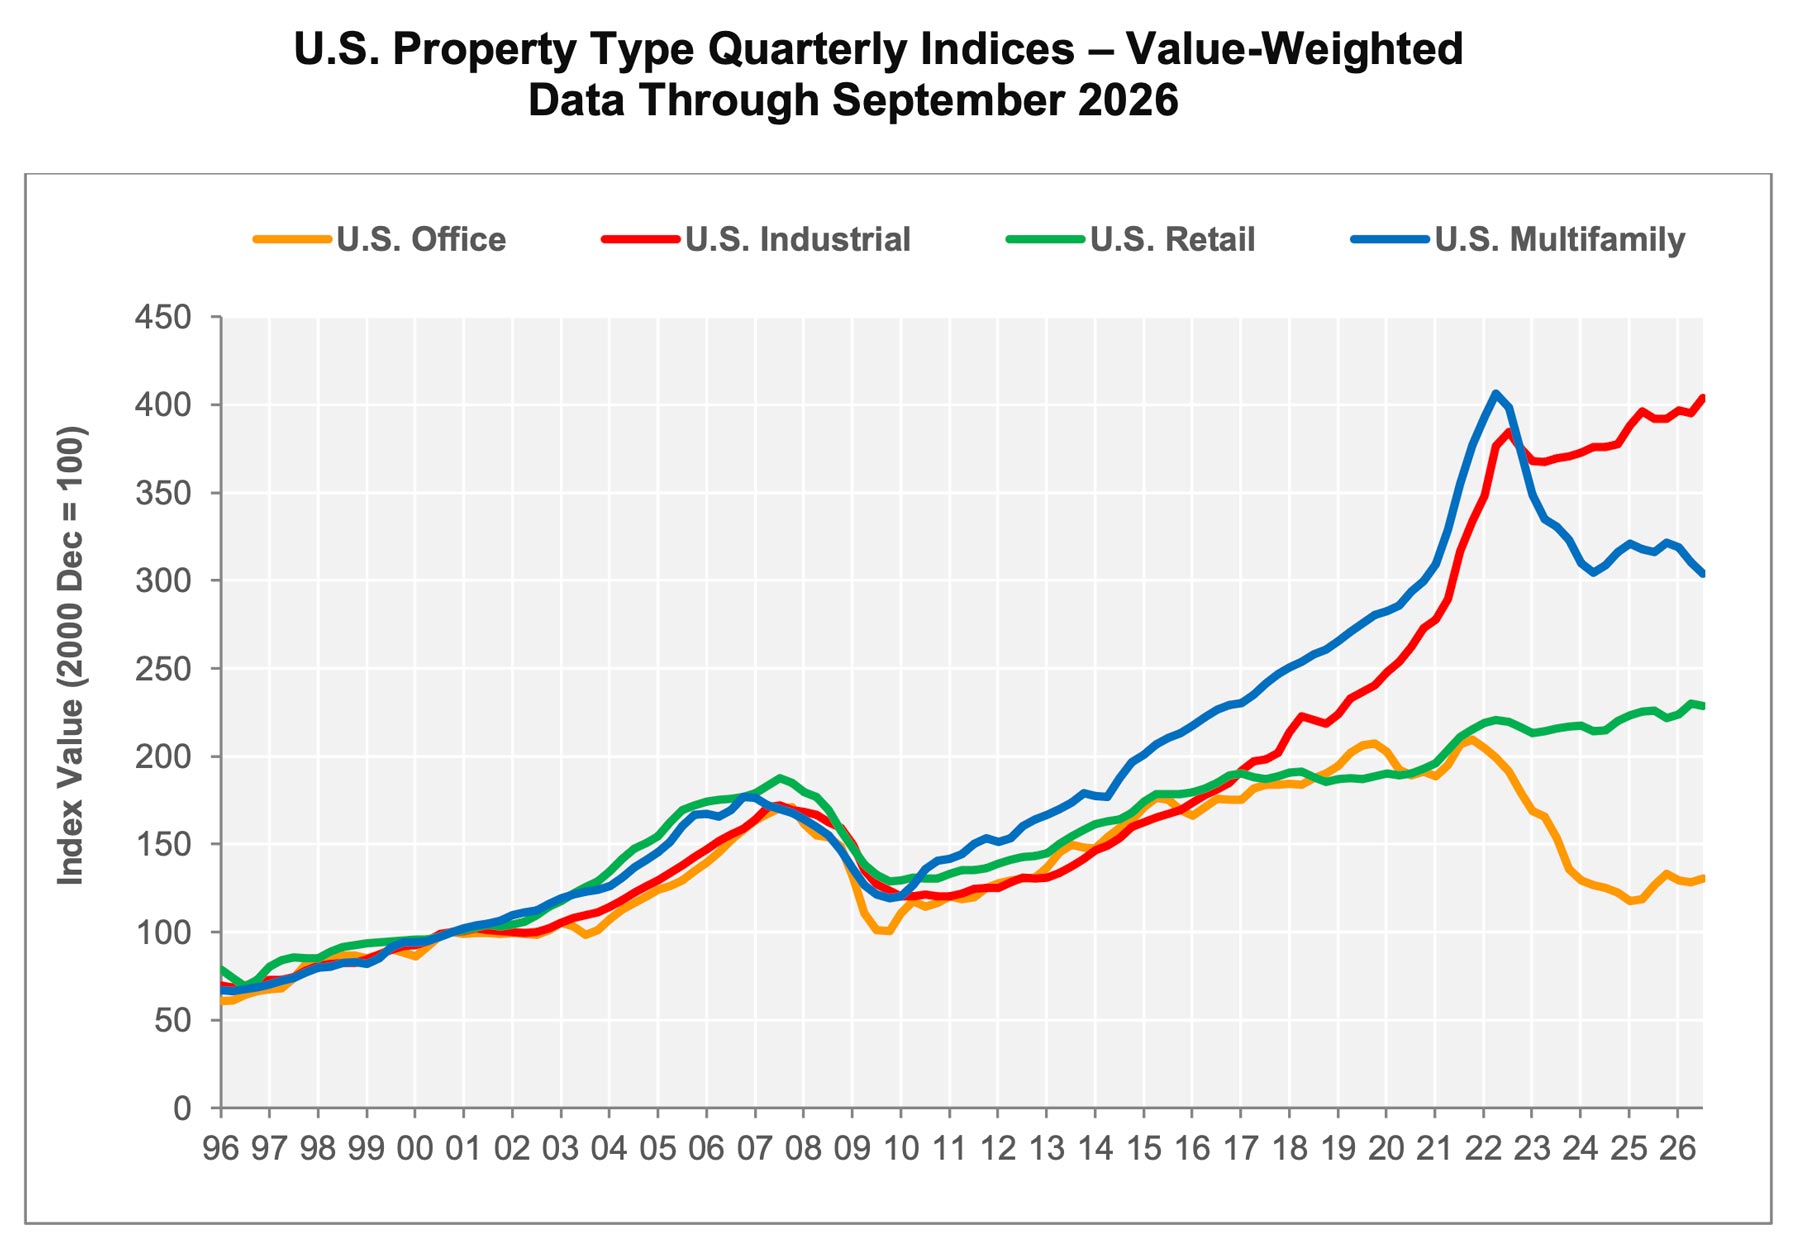
- VALUE-WEIGHTED PRICES ROSE IN THREE OF FOUR PROPERTY TYPES IN THE THIRD QUARTER OF 2026 COMPARED TO LAST YEAR. Industrial led the value-weighted price indices, increasing 3.1% in the 12 months ending in September 2026, followed by office at 2.8% and retail at 1.1% during the same period. Multifamily was the only value-weighted property type to decline, falling 3.9% during the 12 months ending in September 2026.
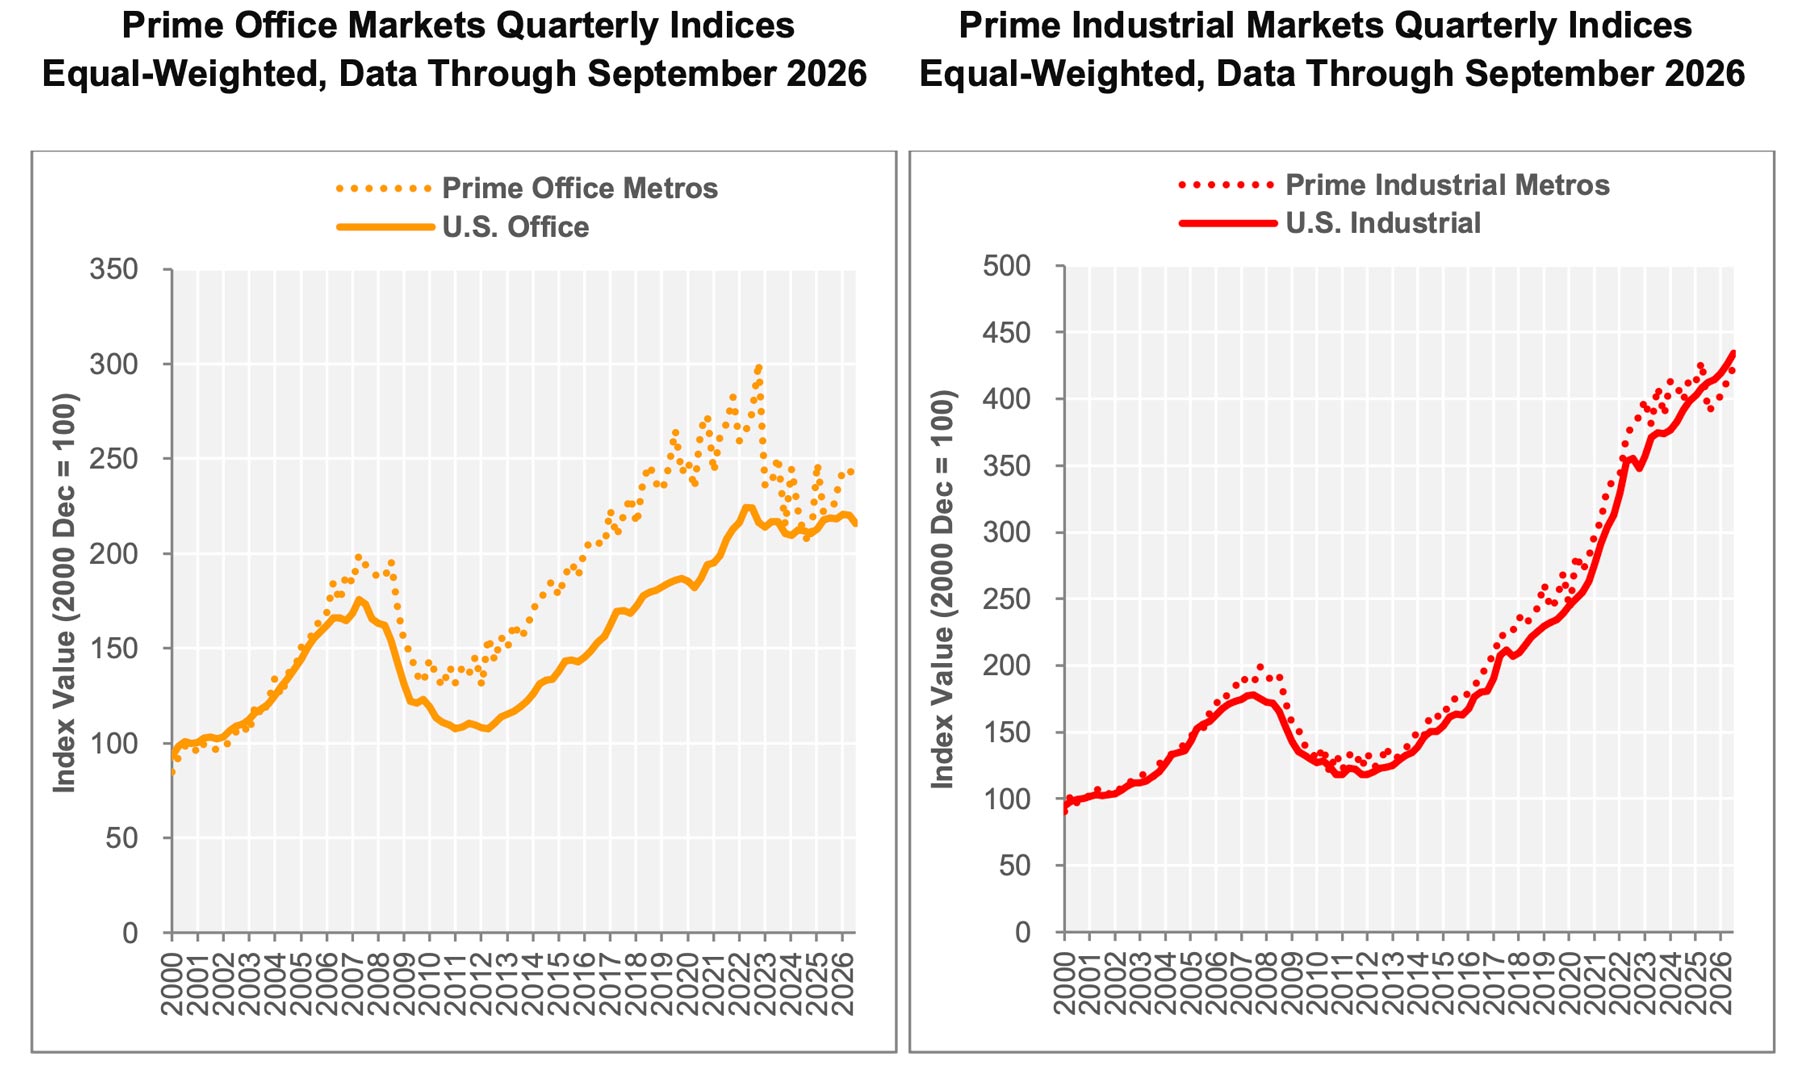
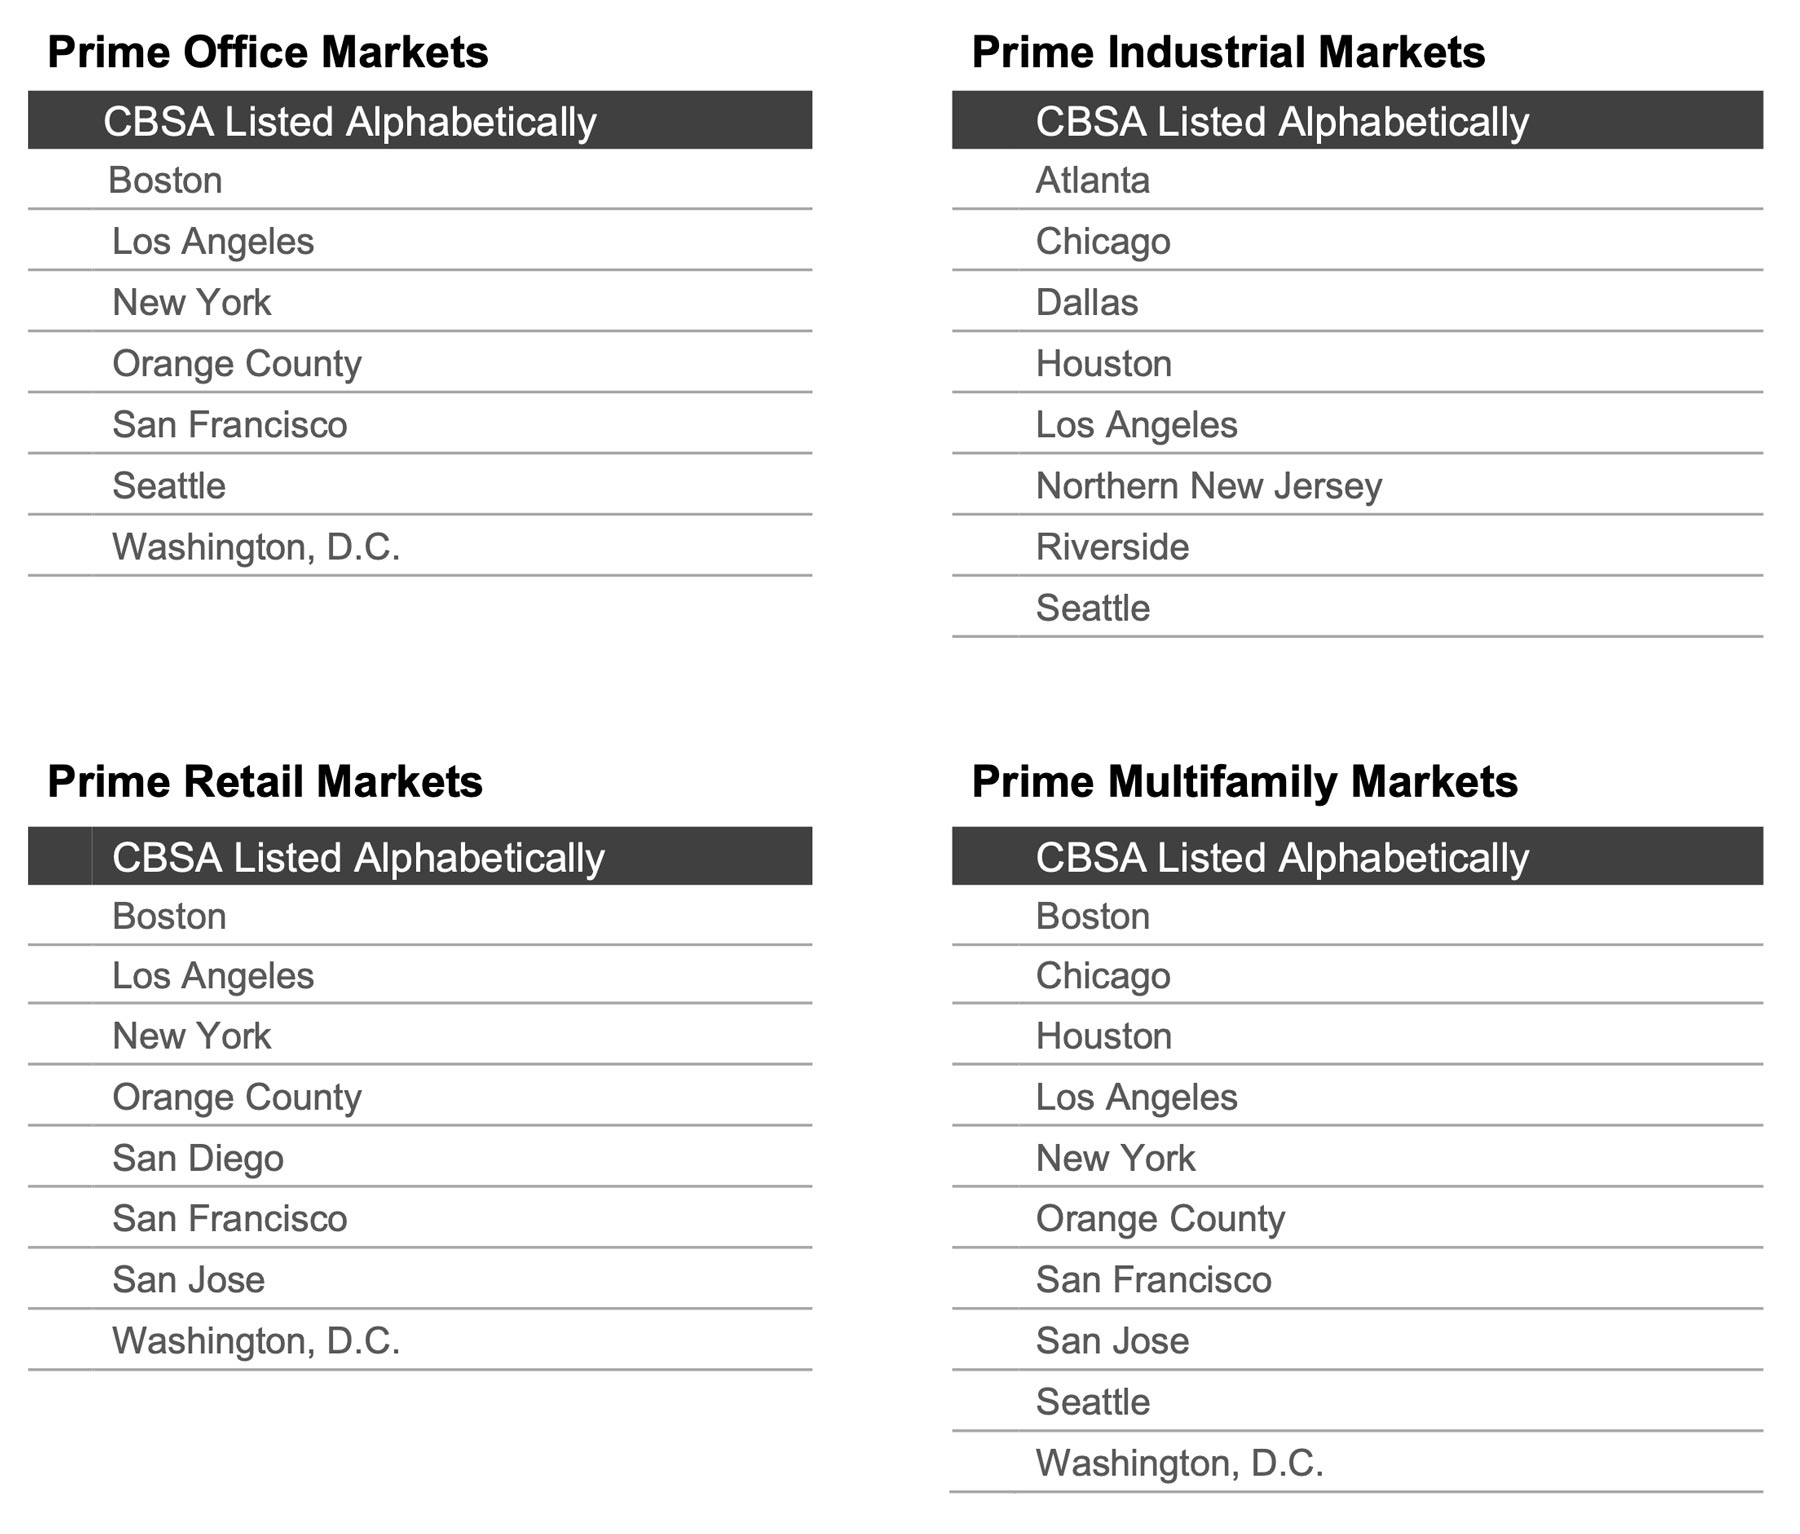
- OFFICE PRICES DIVERGED BY SIZE. Large office properties saw prices climb 2.8% during the 12 months ending in September 2026. Prime office markets posted a stronger gain, as repeat-sale prices in this cohort rose 9.8% during the same period. In contrast, equal-weighted office prices fell 1.5% during the 12 months ending in September 2026.
- INDUSTRIAL PRICES ADVANCED ACROSS SIZES. The equal-weighted pricing segment climbed 5.4% during the 12 months ending in September 2026, while the value-weighted industrial segment rose 3.1% during the same period. Prime industrial markets also gained, rising 8.5% since September 2025.
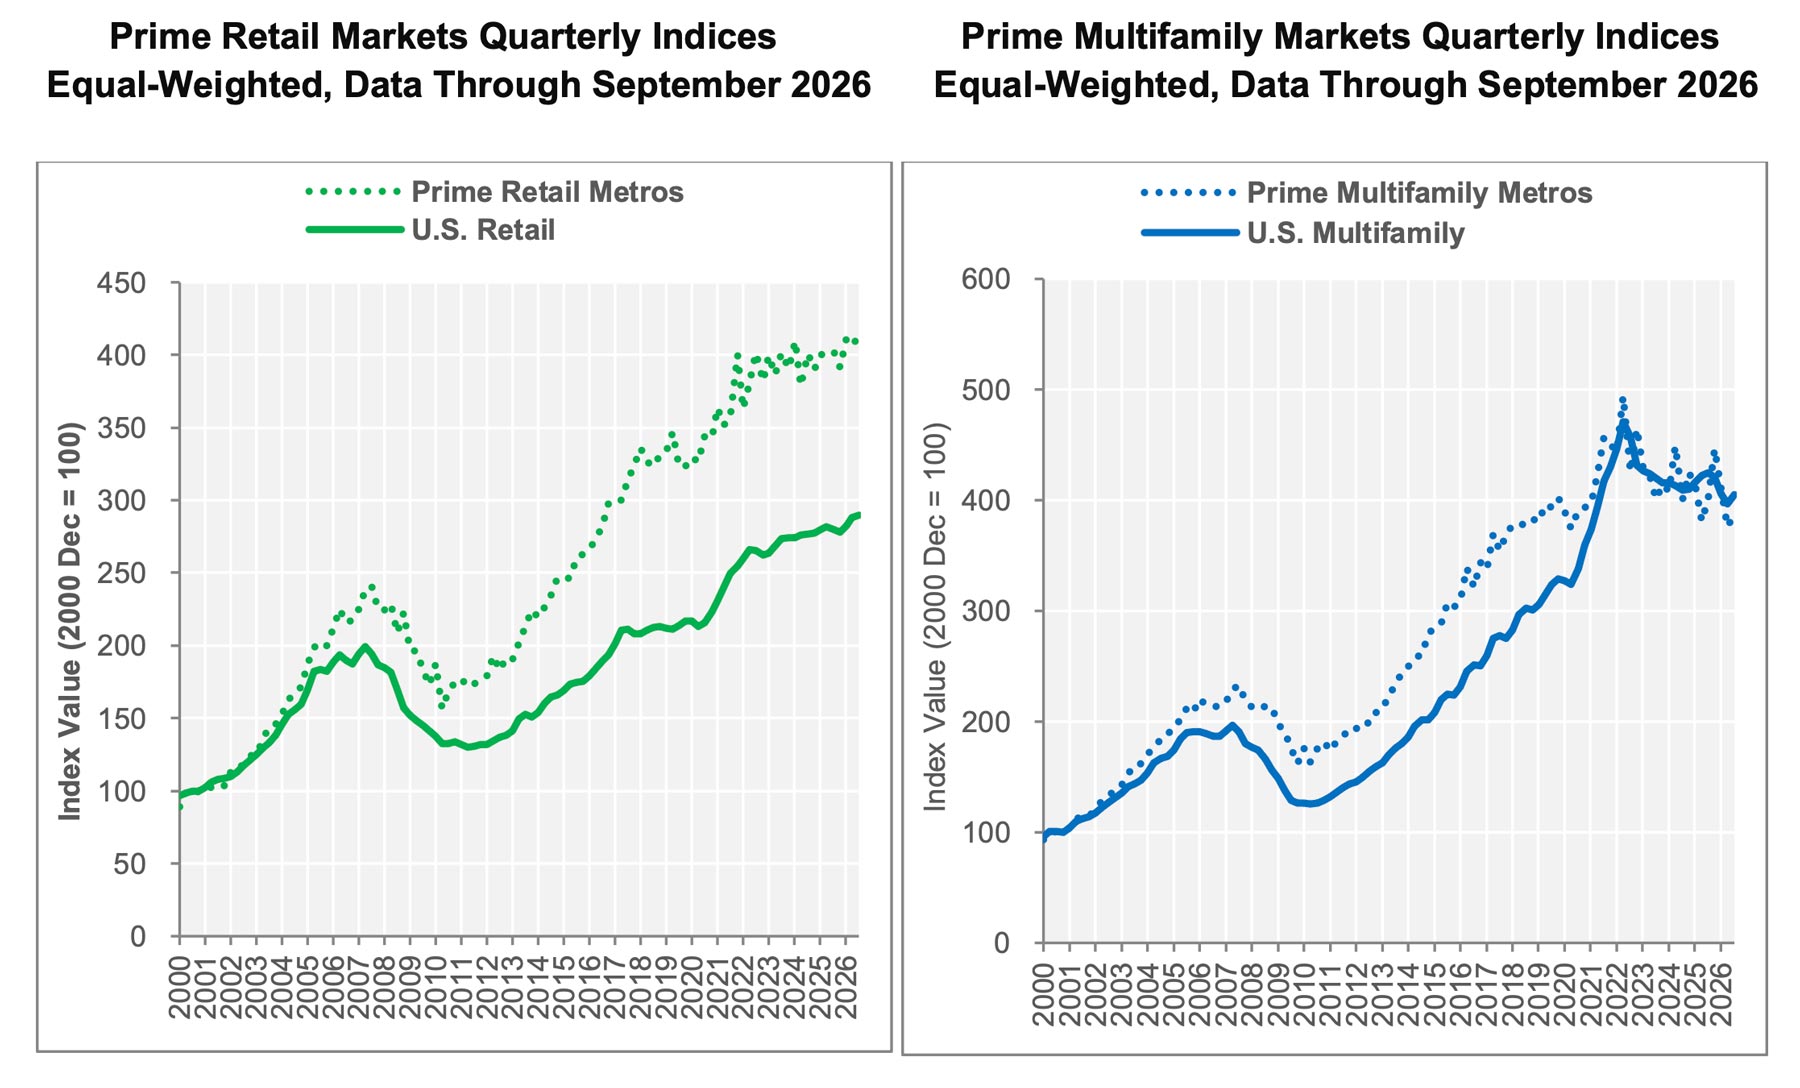
- MULTIFAMILY PRICES DECLINED ACROSS SIZES. Both the equal-weighted and value-weighted multifamily indices declined during the 12 months ending in September 2026, falling 4.6% and 3.9%, respectively. Prime multifamily markets followed the same pattern, with prices falling 3.6% in the 12 months ending in September 2026.
- RETAIL PRICES ROSE ACROSS SIZES. Both equal- and value-weighted indices saw prices increase during the 12 months ending in September 2026, climbing 3.5% and 1.1%, respectively. Prime retail metros saw prices tick up 0.5% in the 12 months ending in September 2026 compared to the 12 months ending in September 2025.
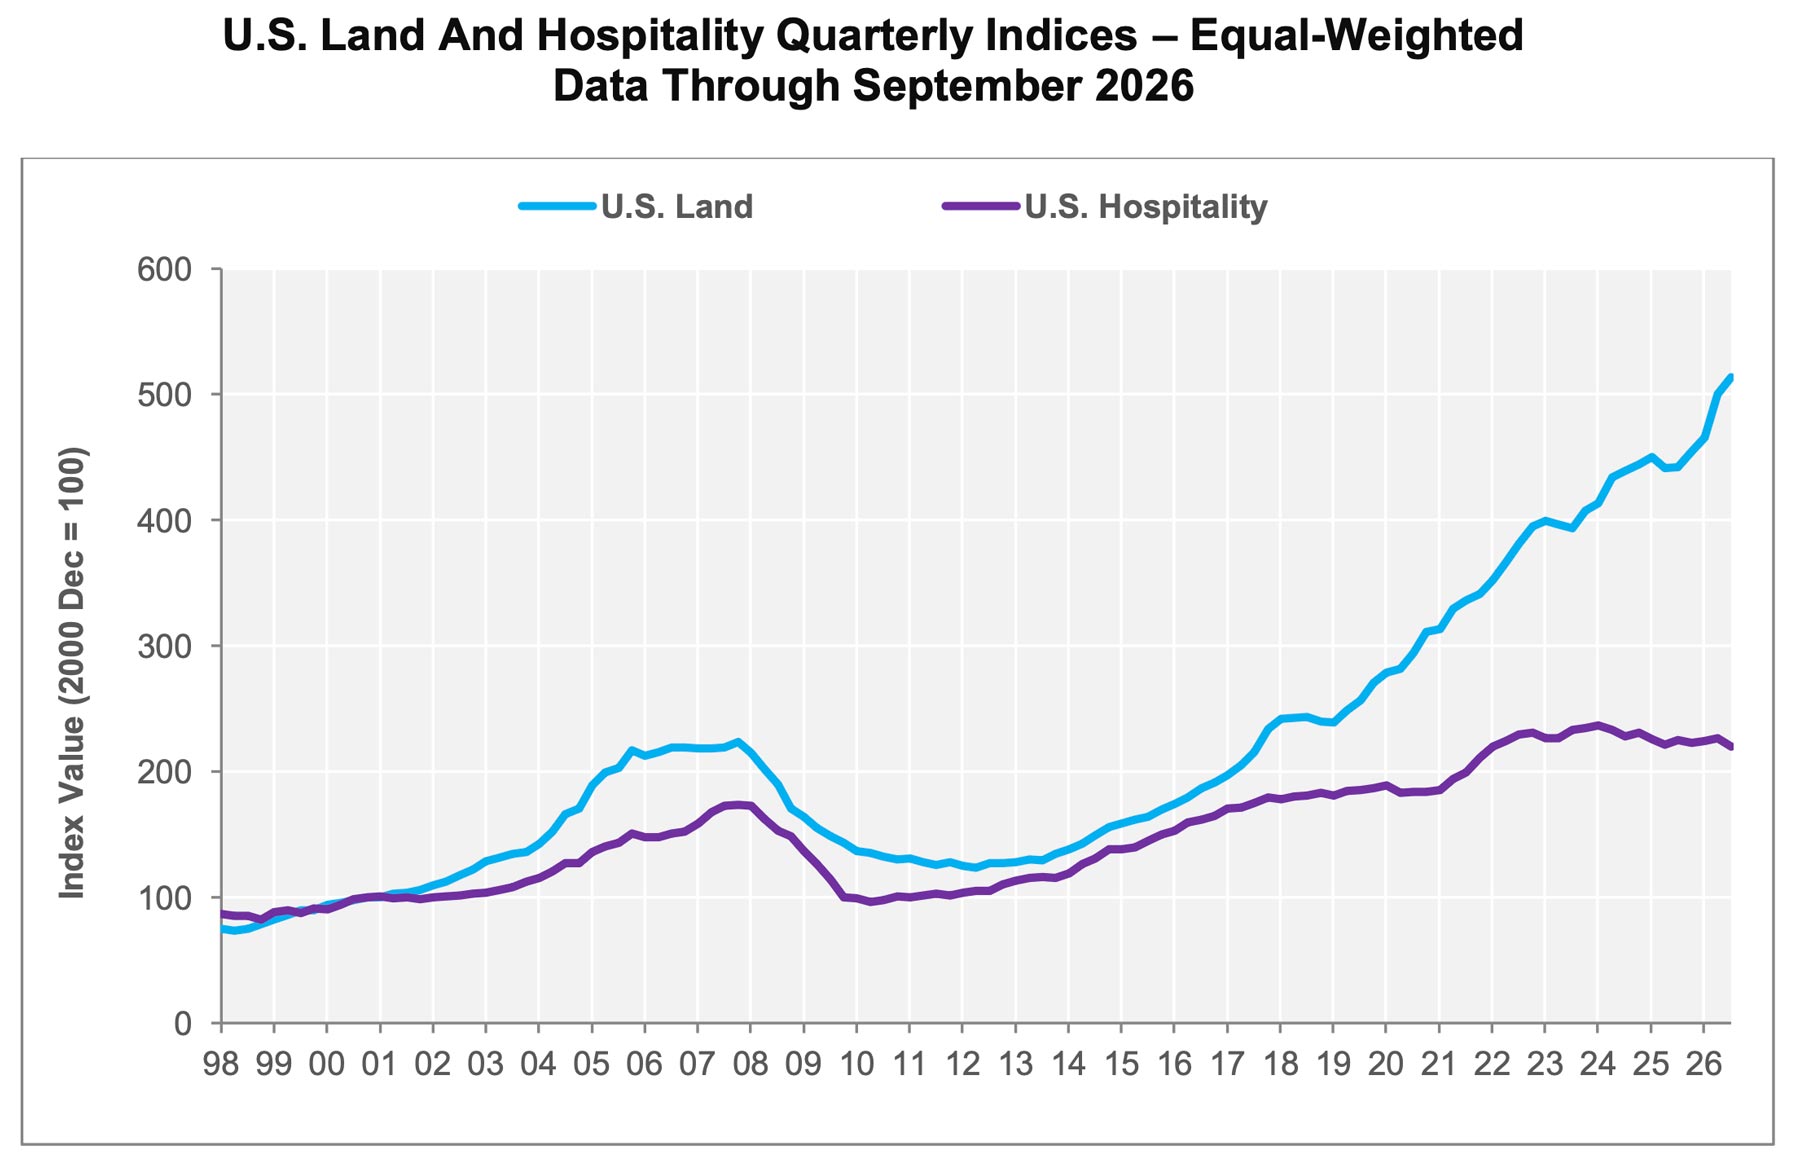
- EQUAL-WEIGHTED HOSPITALITY PRICES DECLINED. The equal-weighted hospitality index fell 2.4% in the third quarter of 2026 compared to the third quarter of 2025 and declined 2.8% compared to the prior quarter ending in June 2026.
- LAND PRICES CONTINUED TO CLIMB IN THE THIRD QUARTER OF 2026. The equal-weighted land index is historically a volatile property type index. It climbed 16.2% in the 12 months ending September 2026 compared to that same period in 2025 and 2.7% compared to the prior quarter ending June 2026.
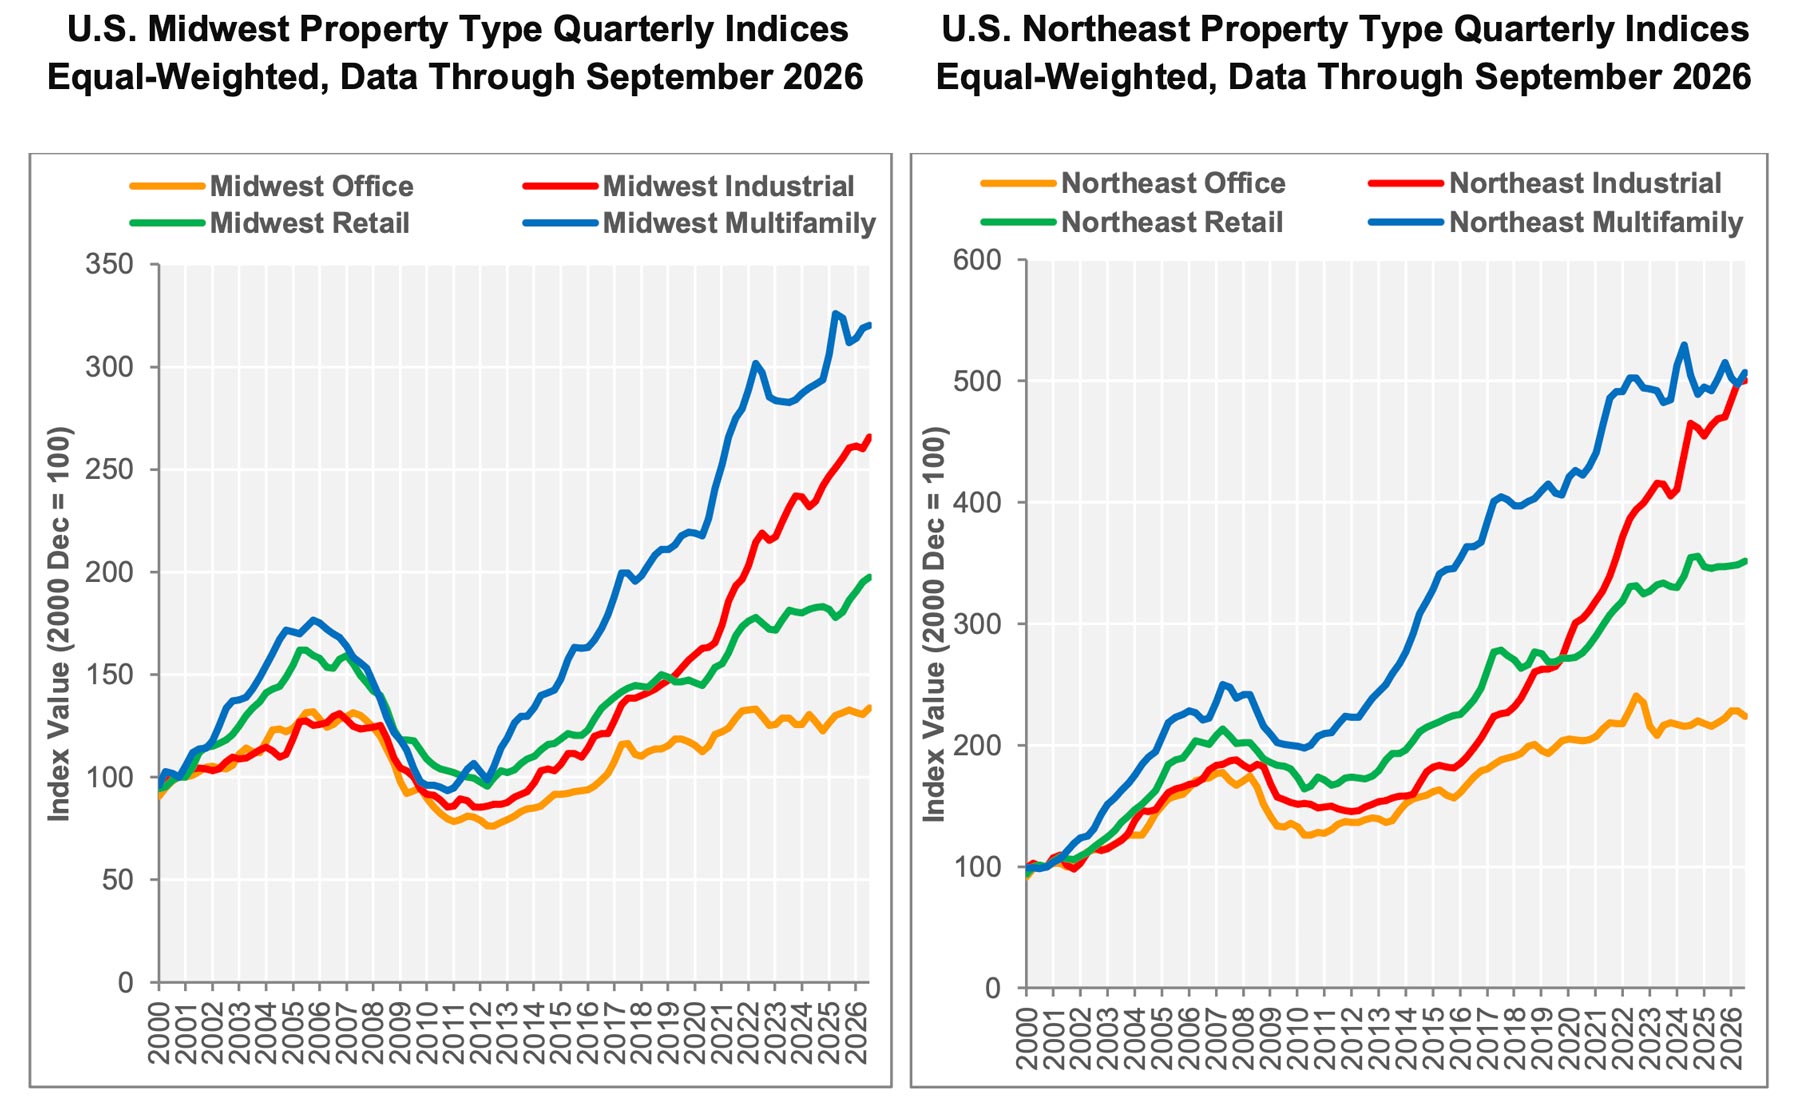
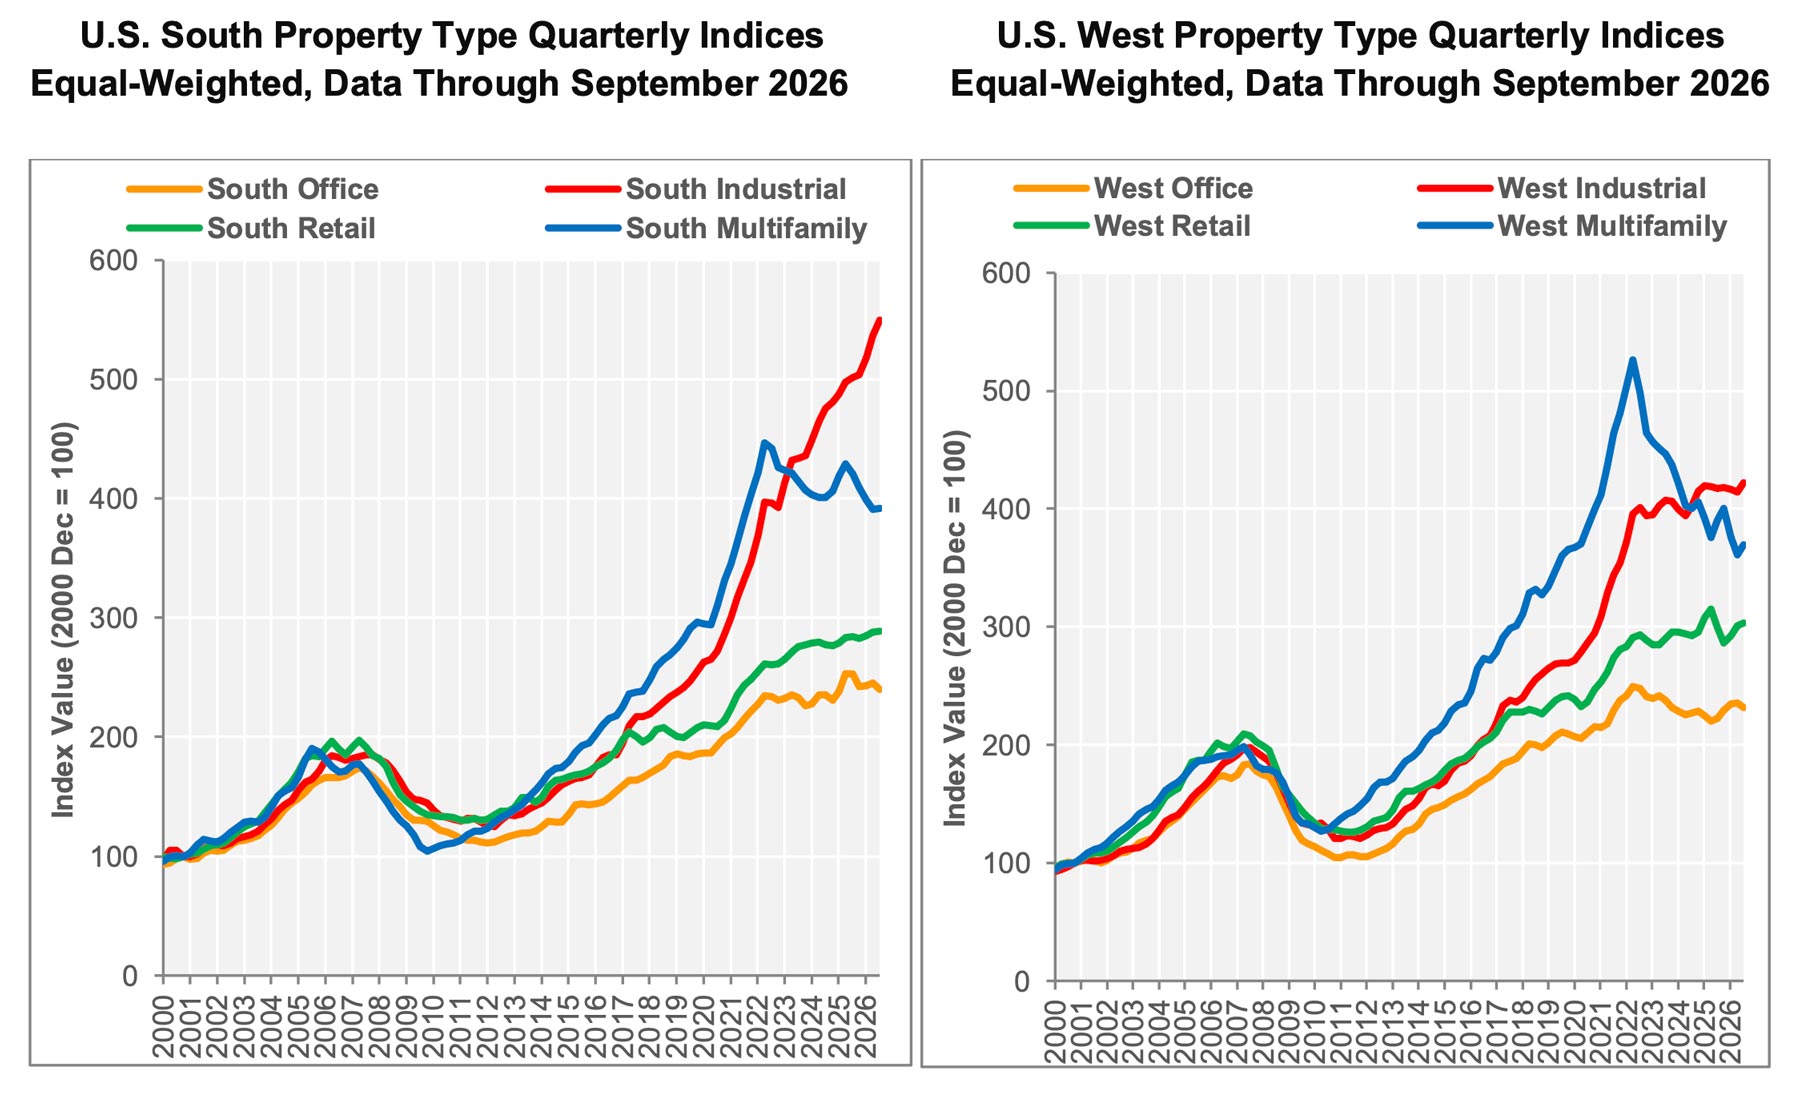
- NORTHEAST VALUE-WEIGHTED INDEX LED REGIONAL PERFORMANCE IN THE THIRD QUARTER OF 2026. The Northeast posted the largest quarterly gain in equal-weighted prices among the four regions, up 2.0% from the second quarter of 2026, and the largest year-over-year gain in value-weighted prices, up 6.4% from the third quarter of 2025. Each geographic region's four main property types produce 16 total property-type regions. All four property types in the Northeast posted positive year-over-year price changes in the third quarter of 2026. The Midwest and West each had three property types with annual gains, while the South had two.
- MIDWEST REGION. The Midwest equal-weighted repeat-sale index increased 1.0% in the third quarter of 2026 over the prior quarter, while the value-weighted index rose 1.9% in the same period. Compared to the third quarter of 2025, the equal-weighted index climbed 5.6%, the largest equal-weighted annual gain among the four regions, while the value-weighted index fell 1.2%. All four property types advanced from the prior quarter: office rose 2.3%, industrial gained 2.1%, retail increased 1.3%, and multifamily edged up 0.5%. Compared to the third quarter of 2025, retail jumped 9.4%, industrial increased 3.9%, and office grew 1.8%, while multifamily declined 1.1%.
- NORTHEAST REGION. The equal-weighted Northeast index rose 2.0% in the third quarter of 2026 compared to the second quarter of 2026 and was 4.1% higher than the prior year. The value-weighted index dipped 0.1% in the third quarter of 2026 but rose 6.4% compared to the third quarter of 2025. Multifamily prices advanced 1.9% compared to the prior quarter, retail gained 0.9%, and industrial edged up 0.3%, while office fell 1.9% in the third quarter of 2026 from the prior quarter. Compared to the third quarter of 2025, industrial prices jumped 6.7%, office rose 2.3%, retail increased 1.3%, and multifamily grew 1.0%.
- SOUTH REGION. The South's equal-weighted repeat-sale index rose 0.6% during the third quarter of 2026 from the prior quarter, while the value-weighted index declined 2.0% in the same period. Compared to the third quarter of 2025, the equal-weighted index increased 1.4%, and the value-weighted index rose 1.9%. Industrial prices climbed 2.4% in the third quarter of 2026 over the prior quarter, while retail rose 0.3% and multifamily edged up 0.2%. Office fell 2.0% from the prior quarter. Compared to the third quarter of 2025, industrial jumped 9.7%, the largest annual gain among the 16 property-type regions, while retail increased 1.7%. Office shed 5.0% of value and multifamily declined 6.9%, the steepest annual decline among the 16 property-type regions, in the third quarter of 2026 compared to the third quarter of 2025.
- WEST REGION. The equal-weighted West index declined 1.4% in the third quarter of 2026 from the prior quarter and was 0.3% lower than the prior year. The value-weighted index decreased 2.0% in the third quarter of 2026 but rose 0.8% compared to the third quarter of 2025. Multifamily climbed 2.3% over the prior quarter, industrial rose 2.0%, and retail increased 0.7%, while office fell 1.8%. Compared to the third quarter of 2025, office was up 3.8%, industrial rose 1.2%, and retail increased 1.1%, but multifamily lost 5.3% of value.
About the CoStar Commercial Repeat-Sale Indices
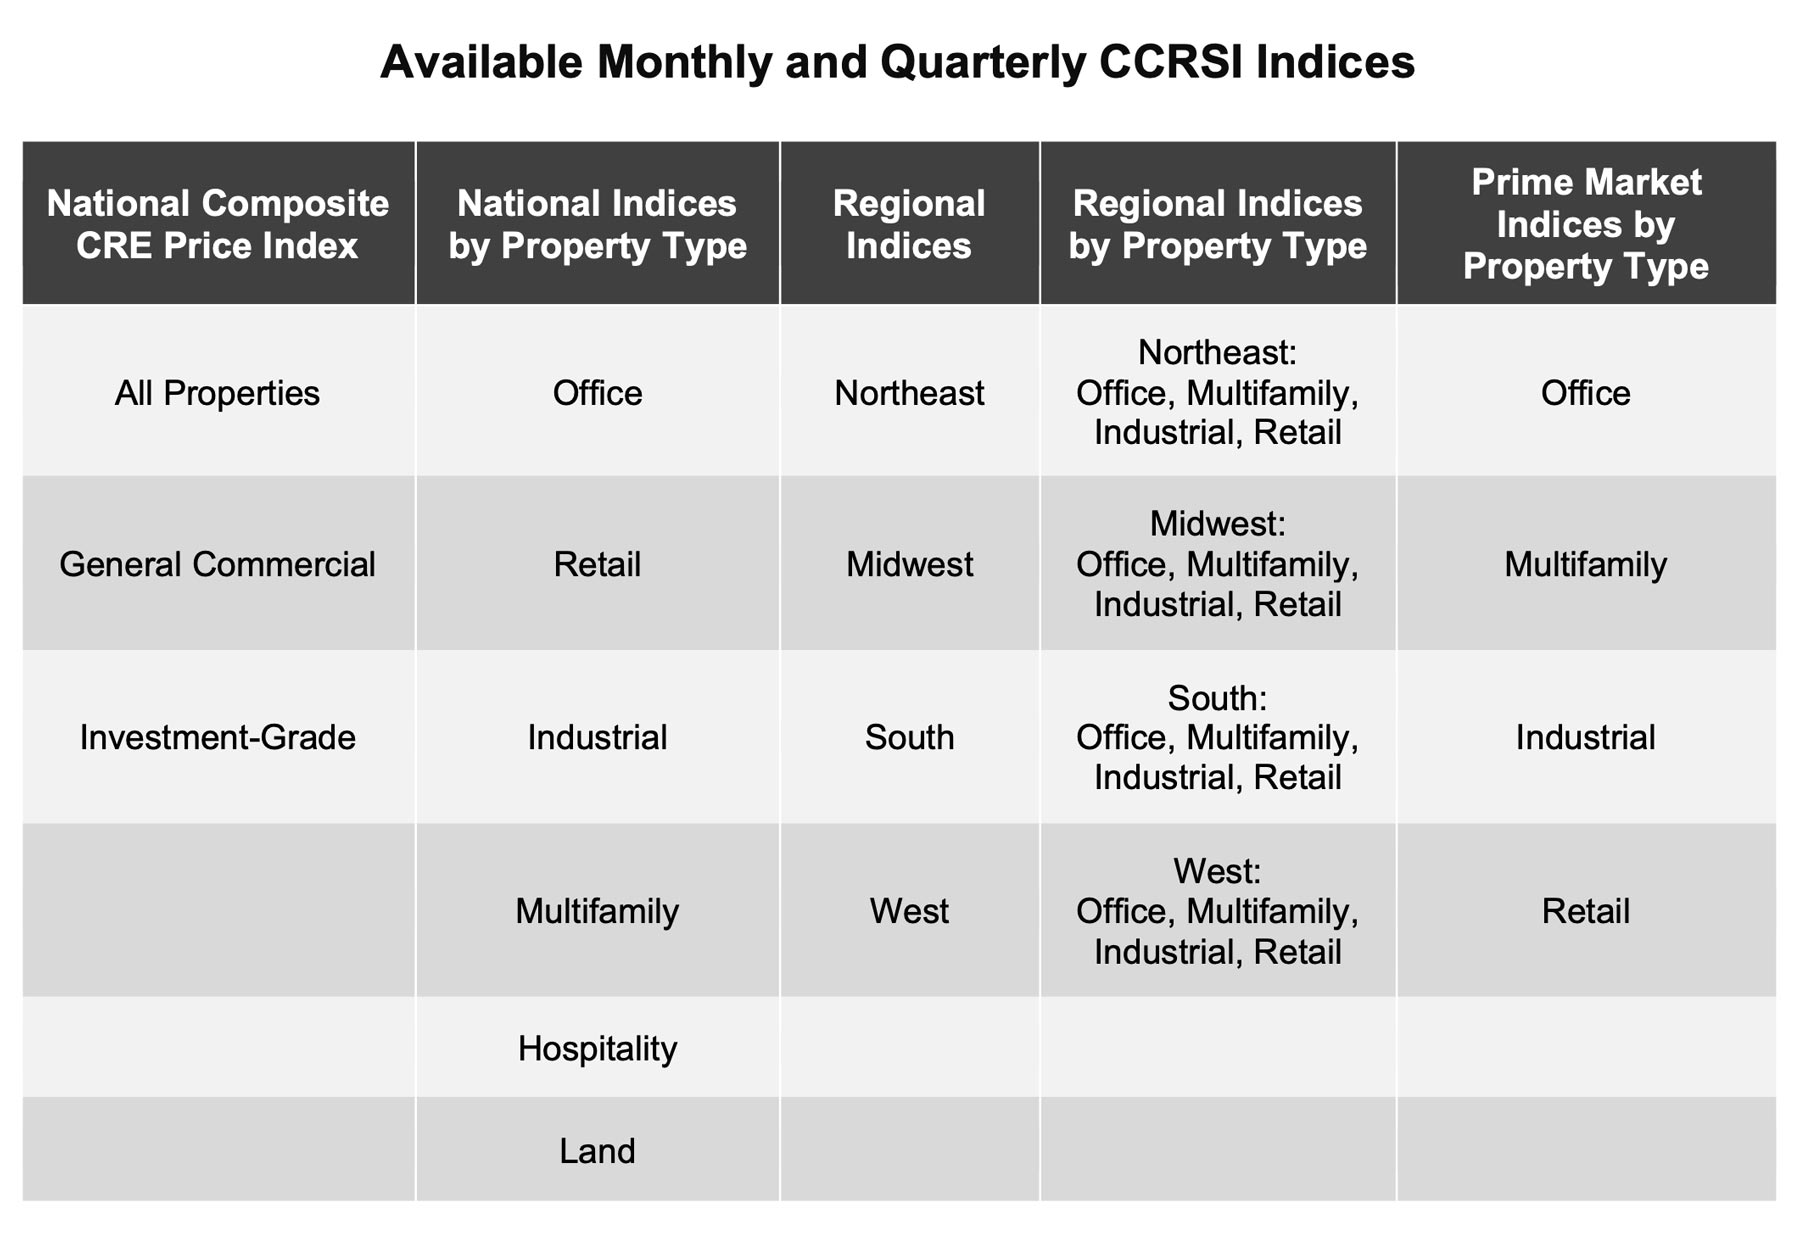
The CoStar Commercial Repeat-Sale Indices (CCRSI) is the most comprehensive and accurate measure of commercial real estate prices in the United States. In addition to the national Composite Index (presented in equal-weighted and value-weighted versions), national Investment-Grade Index, and national General Commercial Index, which we report monthly, we report quarterly on 30 sub-indices in the CoStar index family. The sub-indices include breakdowns by property sector (office, industrial, retail, multifamily, hospitality, and land), by region of the country (Northeast, South, Midwest, and West), by transaction size and quality (general commercial, investment-grade), and by market size (composite index of the prime market areas in the country).
The CoStar indices are constructed using a repeat sales methodology, which is widely considered the most accurate measure of price changes for real estate. This methodology measures the movement in the prices of commercial properties by collecting data on actual transaction prices. A sales pair is created when a property is sold more than once. The prices from the first and second sales are then used to calculate the property's price movement. The aggregated price changes from all the sales pairs create a price index.
MEDIA CONTACT:
Matthew Blocher, Vice President, CoStar Group Corporate Marketing & Communications (mblocher@costar.com).
For more information about the CCRSI Indices, including the complete accompanying data set and research methodology, legal notices and disclaimer, please visit http://costargroup.com/costar-news/ccrsi.
ABOUT COSTAR GROUP
CoStar Group (NASDAQ: CSGP) is a leading global provider of online real estate marketplaces, information, analytics, and digital twins in the property markets. Founded in 1986, CoStar Group is dedicated to digitizing the world’s real estate, empowering all people to discover properties, insights, and connections that improve their businesses and lives.
CoStar Group’s major brands include CoStar, a leading global provider of commercial real estate data, analytics, and news; LoopNet, the most trafficked commercial real estate marketplace; Apartments.com, the leading platform for apartment rentals; Homes.com, the fastest-growing residential real estate marketplace; and Domain, one of Australia’s leading property marketplaces.
CoStar Group’s industry-leading brands also include Matterport, a leading spatial data company whose platform turns buildings into data to make every space more valuable and accessible; STR, a global leader in hospitality data and benchmarking; Zonda, a leading provider of data, analytics, software, and marketplace solutions for the residential construction industry; Ten-X, an online platform for commercial real estate auctions and negotiated bids; and OnTheMarket, a leading residential property portal in the United Kingdom.
CoStar Group’s websites attracted 121 million average monthly unique visitors in the third quarter of 2026, serving clients around the world. Headquartered in Arlington, Virginia, CoStar Group is committed to transforming the real estate industry through innovative technology and comprehensive market intelligence. From time to time, we plan to utilize our corporate website as a channel of distribution for material company information. For more information, visit CoStarGroup.com